Chapter 2
The new spreadsheet was false.
Not completely.
That made it worse.
Some workers had been paid.
Some had been paid late.
Some received cash distributions that matched the event sheets.
Others had smaller balances.
A few had signed acknowledgments.
Forty-three unresolved entries remained on Peter Vale’s reconciliation.
Bellini’s new attachment marked every one:
PAID — CONFIRMED.
Luca looked at Marcus.
“Can we verify?”
“Yes.”
“Without calling workers at midnight?”
“Yes.”
Good.
They preserved the file.
No mass panic calls.
The next morning, independent labor counsel and forensic accountant Lena Cho began review.
Not to turn every service charge into theft.
Important.
Contracts differed.
Some event agreements said:
SERVICE CHARGE RETAINED BY OPERATOR.
Those were not worker pools.
Some said:
SERVICE CHARGE INCLUDES ADMINISTRATIVE AND LABOR ALLOCATION.
Ambiguous.
Some explicitly said:
DISTRIBUTED TO EVENT PERSONNEL.
Those mattered.
Then worker offer letters.
Temporary staff sometimes received:
hourly wage.
event premium.
shared service distribution.
Different.
Peter had covered only amounts he believed were contractually promised.
Good.
No giant “tips stolen everywhere” claim.
Then Lena separated events into categories.
Category A:
Bellini clearly entitled to retain service charge.
No worker claim.
Category B:
mixed wording.
Needs case-by-case reconciliation.
Category C:
client invoice and worker order both promised distribution.
Shortfall.
Nine events.
Forty-three workers.
Total verified preliminary shortfall:
$121,860.
Lower than Peter’s $187,400.
Important.
Peter accepted that.
He had estimated some ambiguous items in workers’ favor.
Good.
Then:
what about remaining sixty-five thousand?
Possible contractual dispute.
Not automatically theft.
Then Luca asked:
“Did Peter overpay?”
Maybe.
He covered some amounts Bellini might not legally owe.
His choice.
Then Peter said:
“I’d rather overpay staff than tell them wait six months.”
Good.
But no canonization.
His company also made errors.
Two worker names duplicated.
one cash payment not logged.
one shift premium miscalculated.
Specific.
Then the false “all paid” spreadsheet.
Who sent it?
Bellini finance controller:
Marta Keene.
She said Vanessa called after dinner.
Told her:
“Close every open worker item.”
Marta asked:
“Paid or accrued?”
Vanessa:
“Mark resolved. We’ll fund tomorrow.”
There.
Not “fake it forever.”
Temporary concealment.
Still false.
Then Marta sent it.
Why?
Fear.
boss.
engagement crisis.
She cooperated.
No criminal mastermind.
Then Vanessa’s personal debt to Peter.
The $187,400 agreement.
Why personal?
Months earlier, Bellini board disputed Peter’s reconciliation.
Vanessa privately said she would cover the whole amount to stop him contacting Moretti clients.
She signed a promissory note.
Then repaid:
$32,000.
$18,000.
Remaining:
$137,400?
But hook says Peter says 187,400. Need consistency. We can say note principal grew with newer shortages. Let's clarify.
Original personal note:
$120,000.
Then new events added.
Vanessa acknowledged further provisional amounts.
Current claim:
$187,400.
Good.
Then wine auction value:
$214,700.
Enough to pay Peter and auction fees.
That was why.
Not collateral.
Not provenance.
Liquidation.
Then Luca’s father’s cellar.
Were bottles actually removed?
No.
Broker had inventoried.
No transfer.
No sale contract signed.
Good.
Attempted unauthorized sale.
Then ownership.
Cellar belonged to Moretti Family Holdings.
Vanessa had no authority.
Broker thought she did because she presented:
event-property disposal authorization.
Fake?
No.
It was a real document authorizing her to dispose of engagement décor and consumable event inventory.
She stretched it to wine cellar.
Bad interpretation.
Broker failed to verify.
Specific.
Then auction house paused.
No loss.
Then Emma.
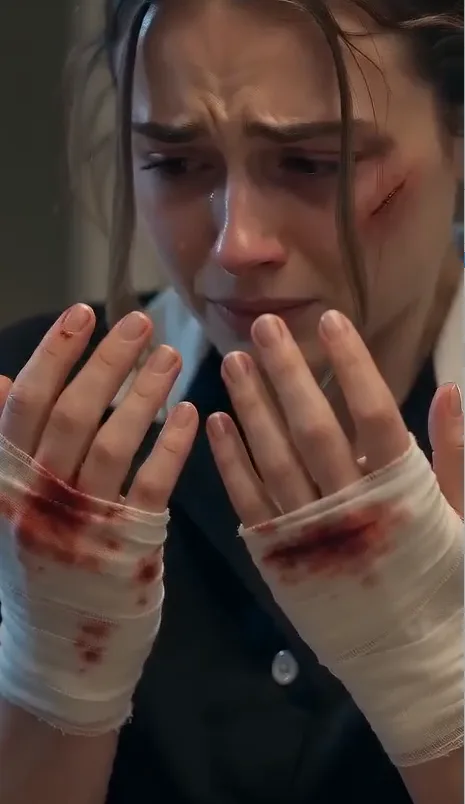
Hospital.
Hands cleaned.
several small sutures.
no tendon damage.
no nerve injury.
cheek cuts superficial.
lip swelling.
bruising.
Painful.
Recoverable.
Then HR offered medical leave.
Emma resigned.
Not immediately from fear.
The next morning.
She thought overnight.
Then:
“I can’t work in that house.”
HR processed.
No NDA.
Reference controlled by HR.
Vanessa had no say.
Then unpaid service distribution.
Emma’s $680.
Verified.
Plus another $240 from spring reception.
She had never known.
Total:
$920.
Not life-changing.
Still hers.
Paid.
Then thirty-eight other workers got verified payments within two weeks.
Five ambiguous claims entered review.
Good.
Then Luca did not personally hand out checks.
Family office processed through counsel and payroll.
No savior theater.
Then Peter’s staffing company.
Moretti paid only amounts Moretti had contractually represented as worker distributions and had funded through invoices.
Bellini remained responsible for other items.
Good.
Then Luca asked:
“Did we pay twice?”
Marcus:
“In some events, yes, if Peter already advanced staff.”
Then repayment goes to Peter for verified advances.
Good.
No double windfall.
Then Moretti’s own failure.
Why did family office code all service charges as pass-through labor?
Because Bellini submitted summaries that said so.
Did anyone reconcile actual worker distributions?
No.
They trusted event manager.
There.
Weak control.
Then Luca asked:
“Why?”
Marcus:
“Personal events weren’t audited like corporate events.”
Good.
Then:
“Because?”
“Because they were considered private spending.”
Still money.
Still workers.
Then family office changed:
event service-charge coding must match contract.
pass-through worker distributions require post-event reconciliation.
related-party manager cannot self-certify.
Good.
Then Emma’s new job.
Boutique hotel.
Banquet operations assistant.
Supervisor:
Maya Chen.
First day, Maya handed her event-close checklist.
Line:
SERVICE CHARGE / GRATUITY DISTRIBUTION VERIFIED.
Emma stared.
Maya noticed.
“You okay?”
“Yes.”
Then:
“Do you want me to explain?”
“Yes.”
Good.
Maya explained:
hotel service charge partly retained.
gratuity pool separate.
staff receive written formula.
Clear.
Emma almost cried.
Not because sad.
Because clarity felt strange.
Then Luca texted:
I heard you found new work. Congratulations.
Emma replied:
Thank you.
No coffee.
Good.
Then Peter’s records uncovered something else.
Vanessa had not created the service-charge structure.
Her father’s company had used it for years.
Some contracts were clear.
Some were not.
Then one old Bellini event manager said:
“We were taught to treat service charge as flexible margin.”
There.
Culture.
Then:
“Even when client thought workers got it?”
He looked down.
“That was the problem.”
Good.
Not one woman inventing everything.
Then the engagement cancellation.
Vendors wanted deposits.
Some nonrefundable.
Luca paid lawful cancellation fees.
No attempt to punish innocent vendors.
Then one Bellini-linked florist voluntarily returned part of markup after learning conflict had not been disclosed.
Good.
Another refused.
Litigation.
Fine.
Then Peter asked:
“What about my remaining disputed amount?”
Lena:
“Prove it.”
He smiled.
“Fair.”
Good.
The case became accounting.
Less dramatic.
More trustworthy.
And for Emma, that was the first sign life might stop feeling like someone else’s emergency.
The auction broker cooperated immediately. He had received photographs, inventory estimates, and Vanessa’s claimed disposal authority. He had not received ownership documents. His firm changed procedure afterward: family possession is not proof of title. No wine left the property.
At the boutique hotel, Emma learned staff could see their expected event premium before clock-in. One bartender challenged a number. Payroll corrected it before shift ended. Emma stared. A question did not become insubordination. That mattered.
The second chapter made the accounting smaller and stronger. Not every service charge belonged to staff. Not every claim was valid. The verified shortfalls were enough.
The second chapter made the accounting smaller and stronger. Not every service charge belonged to staff. Not every claim was valid. The verified shortfalls were enough.
The second chapter made the accounting smaller and stronger. Not every service charge belonged to staff. Not every claim was valid. The verified shortfalls were enough.
The second chapter made the accounting smaller and stronger. Not every service charge belonged to staff. Not every claim was valid. The verified shortfalls were enough.
The second chapter made the accounting smaller and stronger. Not every service charge belonged to staff. Not every claim was valid. The verified shortfalls were enough.
The second chapter made the accounting smaller and stronger. Not every service charge belonged to staff. Not every claim was valid. The verified shortfalls were enough.
The second chapter made the accounting smaller and stronger. Not every service charge belonged to staff. Not every claim was valid. The verified shortfalls were enough.
The second chapter made the accounting smaller and stronger. Not every service charge belonged to staff. Not every claim was valid. The verified shortfalls were enough.
The second chapter made the accounting smaller and stronger. Not every service charge belonged to staff. Not every claim was valid. The verified shortfalls were enough.
The second chapter made the accounting smaller and stronger. Not every service charge belonged to staff. Not every claim was valid. The verified shortfalls were enough.
The second chapter made the accounting smaller and stronger. Not every service charge belonged to staff. Not every claim was valid. The verified shortfalls were enough.
The second chapter made the accounting smaller and stronger. Not every service charge belonged to staff. Not every claim was valid. The verified shortfalls were enough.
The second chapter made the accounting smaller and stronger. Not every service charge belonged to staff. Not every claim was valid. The verified shortfalls were enough.
May you like
The second chapter made the accounting smaller and stronger. Not every service charge belonged to staff. Not every claim was valid. The verified shortfalls were enough.
The second chapter made the accounting smaller and stronger. Not every service charge belonged to staff. Not every claim was valid. The verified shortfalls were enough.