Chapter 2
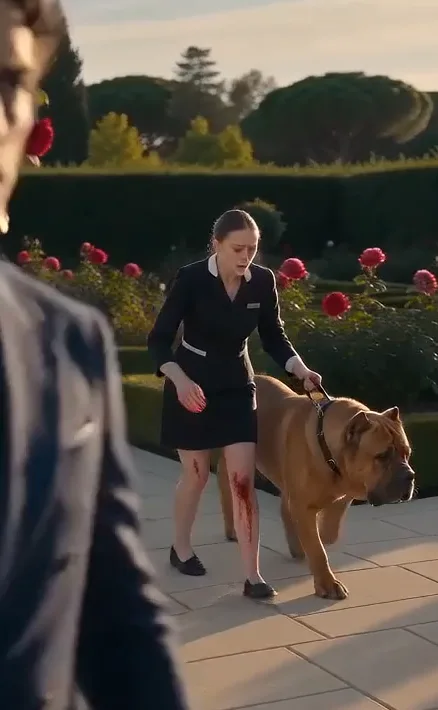
The greenhouse audit began the next morning.
Not with police tape everywhere.
With photographs.
inventory.
vendor records.
chemical safety review.
The solvent can was ordinary mineral spirits.
Used to remove adhesive labels and help burn paper scraps.
No elaborate accelerant plot.
Still improper.
The scorched papers were recoverable in part.
Enough.
Then Rafael March.
He did not flee.
He arrived with a lawyer.
March & Vale Landscape Services had worked for the Moretti estate for eleven years.
Before Vanessa.
That mattered.
Real company.
real crews.
real work.
The question was not:
did they exist?
The question was:
what had been inflated?
Forensic accountant Lena Ortiz took over.
She built categories.
Tree purchases.
soil amendments.
seasonal labor.
irrigation repairs.
pest treatment.
decorative installations.
emergency storm work.
Then actual support:
delivery receipts.
crew logs.
nursery invoices.
equipment records.
gardener diaries.
Good.
No guessing.
The first shock:
most invoices were legitimate.
About eighty percent.
That made the scheme harder to see.
Then the inflated pieces.
Example:
twelve mature pear trees billed.
Six delivered.
Supplier invoice:
six.
Moretti invoice:
twelve.
Difference:
$9,600.
Then frost cloth.
Invoice:
4,000 yards.
Supplier:
2,100.
Difference:
$5,700.
Then winter labor:
eight workers for five days.
Crew logs:
five workers for four days.
Difference:
$6,400.
Then fungicide application:
billed monthly.
Garden records:
three actual treatments.
Difference:
$8,900 across season.
Not every line enormous.
Together:
meaningful.
Then kickback flow.
Rafael did not simply hand Vanessa half.
Some money went through:
gift cards.
cash reimbursements.
designer furniture purchases.
spa accounts.
travel credits.
cash envelopes.
Messy.
Not sophisticated laundering.
Personal corruption.
Then why?
Rafael’s company had lost municipal landscaping contracts.
Moretti estate work became valuable.
Vanessa controlled approvals.
He paid for continued preference.
Then Luca asked:
“Was she funding the wedding?”
Lena:
“Some benefits covered personal expenses.”
Then:
“Some appear to have been reinvested in Bellini event décor.”
Interesting.
Vanessa sometimes used estate kickbacks to subsidize lavish event production, then received praise for keeping those events “within budget.”
There.
She inflated garden spending to make social events look cheaper.
Cross-subsidy.
Luca stared.
“So the gardens paid for parties.”
“Partly.”
That hurt.
Because Lucia’s conservation program funded beauty, not vanity.
Then Emma.
I resigned that morning.
HR offered leave.
I said:
“No.”
I could not walk through the greenhouse again as an employee.
Reference centralized.
No NDA.
Medical expenses covered.
Workers’ compensation.
Good.
Then the new-job question.
Not immediate.
I rested.
Legs healed.
Bruno?
That was harder.
He waited outside the staff cottage the next morning.
The kennel attendant texted:
“He keeps looking for you.”
I cried.
Not because injured.
Because dogs do not understand resignation.
Luca texted:
Bruno is waiting outside your old entrance.
I replied:
Please don’t bring him.
Then:
Not yet.
He answered:
Understood.
Good.
Then contractor interviews.
Miguel Santos.
Head gardener.
He kept notebooks.
Old-school.
Dates.
weather.
crew count.
planting.
Those notebooks became crucial.
Not secret evidence.
Work records.
He said:
“I complained because numbers didn’t match.”
To whom?
Estate manager.
Estate manager:
Paul Keene.
Paul admitted:
Vanessa said March handled bundled seasonal services.
He stopped checking detail.
Why?
Vanessa was Luca’s fiancée.
Again.
Then Luca:
“Did I ever tell you she had authority?”
Paul:
“No.”
“Then why?”
Paul looked down.
“Because everyone assumed.”
There.
Household governance failure.
Then Moretti family office.
Landscape spending was treated as estate-maintenance discretionary expense.
Annual budget:
about $1.2 million.
Enough room.
Actual kickback scheme over three years:
preliminary $163,400.
Not enormous beside the estate.
Exactly why hidden.
Then Lucia’s original conservation records.
They showed how the program was supposed to work:
independent nursery quotes.
seasonal treatment logs.
tree replacement maps.
gardener signoff.
After her death:
controls weakened.
Then after Vanessa:
vendor approval consolidated.
She did not create every weakness.
She exploited them.
Good.
One old memo required:
ALL MAJOR TREE REPLACEMENTS REQUIRE NURSERY DELIVERY CONFIRMATION.
Simple.
Control once existed.
No one removed it.
A later software migration simply stopped carrying that field forward.
There.
System drift.
Then Rafael March’s lawyer offered cooperation.
He admitted:
inflating quantities.
providing benefits to Vanessa.
backdating one treatment log.
He denied:
burning records.
threatening Emma.
Evidence supported that.
Then one surprising payment.
Rafael had given Miguel $500 at Christmas.
Kickback?
Miguel looked horrified.
“It was a holiday envelope.”
Was it disclosed?
No.
But no evidence of quid pro quo.
Lena classified:
gift-policy issue.
not conspiracy evidence.
Good.
Precision.
Then the chemical boxes in utility closet.
Why stored?
Rafael bought them to create delivery evidence but planned to use them later on another client.
Fraud.
Supplier serials matched.
Then one invoice:
$18,600 orchard conservation.
Actual:
$10,400.
Difference:
$8,200.
Handwritten split:
V.B. 3,200.
R.M. 5,000.
Clear.
Then Vanessa’s suitcase.
Why in the archive?
The private storage room had no camera and little traffic.
Then:
“How did she get the key?”
Paul had issued a duplicate after Vanessa claimed she needed event floral storage.
Again.
No formal authorization.
Then system reform:
restricted-room key checkout.
named purpose.
return date.
access log.
Not cameras everywhere.
Good.
Then my legs.
Cuts healing.
Bruises yellowing.
One afternoon, I walked around my apartment.
No limp.
Small victory.
Then Luca emailed:
Coffee when you’re ready.
I stared.
Not yet.
Replied:
Not yet.
He answered:
Understood.
Good.
Then Bruno.
He stopped waiting by the staff entrance after a week.
That made me cry more.
Healing is strange.
Then Lena called because I had witnessed the suitcase.
Formal statement.
I gave it.
No need to reenter the mansion.
Then she told me:
“The fraud is smaller than people will say.”
“What do you mean?”
“Most landscaping work was real.”
Good.
Then:
“That matters.”
Yes.
Because truth did not need exaggeration.
Lena’s first full reconciliation found one invoice where March & Vale had actually underbilled Moretti by $2,300 after a storm emergency.
She left it in the report.
Fraud review does not mean every discrepancy points one direction.
Then the auction? There was no auction.
No grand asset plot.
No inheritance.
Just maintenance money hiding inside routine invoices.
My final household paycheck included unused leave and workers’ compensation processing.
No hush bonus.
That mattered more than any private envelope would have.
By the time the first audit phase closed, the Moretti gardens were still green.
Trees lived.
roses bloomed.
fountains worked.
The scheme hid inside real work.
That was the lesson.
Fraud does not always look like an empty project.
Sometimes the trees are real.
Only the quantities are not.
The audit also reviewed fuel receipts, because small engines and delivery trucks made them variable. No kickback pattern there. Lena marked the category clean. A useful investigation has to be willing to find nothing.
Paul Keene asked whether he should resign. Luca said the board would decide discipline, not guilt by embarrassment. Paul stayed through the control transition, then later moved to another estate on an ordinary reference.
The second audit week ended with a clean fountain-pump invoice. Lena left it in the sample set deliberately. Controls should prove honest work too. Otherwise every review becomes a machine designed only to accuse.
The second audit week ended with a clean fountain-pump invoice. Lena left it in the sample set deliberately. Controls should prove honest work too. Otherwise every review becomes a machine designed only to accuse.
The second audit week ended with a clean fountain-pump invoice. Lena left it in the sample set deliberately. Controls should prove honest work too. Otherwise every review becomes a machine designed only to accuse.
The second audit week ended with a clean fountain-pump invoice. Lena left it in the sample set deliberately. Controls should prove honest work too. Otherwise every review becomes a machine designed only to accuse.
The second audit week ended with a clean fountain-pump invoice. Lena left it in the sample set deliberately. Controls should prove honest work too. Otherwise every review becomes a machine designed only to accuse.
The second audit week ended with a clean fountain-pump invoice. Lena left it in the sample set deliberately. Controls should prove honest work too. Otherwise every review becomes a machine designed only to accuse.
The second audit week ended with a clean fountain-pump invoice. Lena left it in the sample set deliberately. Controls should prove honest work too. Otherwise every review becomes a machine designed only to accuse.
The second audit week ended with a clean fountain-pump invoice. Lena left it in the sample set deliberately. Controls should prove honest work too. Otherwise every review becomes a machine designed only to accuse.
The second audit week ended with a clean fountain-pump invoice. Lena left it in the sample set deliberately. Controls should prove honest work too. Otherwise every review becomes a machine designed only to accuse.
May you like
The second audit week ended with a clean fountain-pump invoice. Lena left it in the sample set deliberately. Controls should prove honest work too. Otherwise every review becomes a machine designed only to accuse.
The second audit week ended with a clean fountain-pump invoice. Lena left it in the sample set deliberately. Controls should prove honest work too. Otherwise every review becomes a machine designed only to accuse.